

Hello Capitalists!
Get the edge on what you need to know today:
Bitcoin crashes below $60,000 for its worst month since 2022
Apple quietly pulls AI agent job listing as Ternus accelerates
Anthropic plunges 10% one day after its record IPO
Anthropic shares fell 10% Friday in their first full trading day after a historic $93.5 billion IPO, as Nvidia, AMD and other AI names sank amid broader tech pressure.

Greenshoe lifts total: Underwriters exercised the overallotment, adding $12.2 billion to Wednesday’s $81.3 billion raise for an aggregate 1.127 billion shares sold at $83.
Thursday close and open: Shares opened at $111.50 Thursday and closed at $97.17 before the Friday slide to roughly $87.
Bessent praises origins: Treasury Secretary Scott Bessent called it an “only in America story,” noting one co-founder plans a large gift to Trump Accounts.
Mixed analyst views: Seaport assigned neutral, citing the valuation leap and growth needs, while William Blair set outperform on efficiency and long-term profitability potential.
Your money matters.
We are not going anywhere.

The climb ahead is steep and the market can be cruel. But Americans built fortunes from raw ambition! The railroad barons who opened a continent, the oil wildcatters who drilled through dry holes until the gusher hit, the traders who turned American free enterprise into the world’s capital of capital.
They went through worse and they bet everything on the American idea that markets and drive create wealth. We will not watch that edge get dulled.
We press for prosperity every session, even through the drawdowns, the way the builders of this country did.
All of us here at The Capitalist appreciate your support, your loyalty and time you take to read us everyday, so we make this promise to you.
Your money matters. We will staff the desks that bring you the news and information that matters so you can do what you do best, build your American Dream.
We are not going anywhere.
Bitcoin crashes below $60,000 for its worst month since 2022
Bitcoin plunged below $60,000 Friday, down 23% in November and on track for its worst month since June 2022, as capital rotated toward major IPOs and the coin tracked risk assets rather than hedging them.

Pre-IPO pattern repeats: It dropped 22.7% in the 30 days before Anthropic’s debut and 22.3% ahead of SpaceX’s June listing, with ether falling similarly.
ETF outflows add pressure: U.S. spot bitcoin ETFs saw roughly $3.5 billion in net withdrawals this month, including $582 million Thursday.
Fails digital-gold test: Experts note rising correlation with the Nasdaq-100 and stocks, as gold itself fell over 35% from its 2026 peak amid higher rates.
Support range in focus: Analysts flag $60,000–$62,000 as critical; a break could retest the July low near $57,737 while corporate treasuries and DATs amplify swings.
SanDisk sinks after its 8-for-1 split as chips get crushed
SanDisk stock began trading Friday on an 8-for-1 split basis near $88 after closing above $755 Thursday, falling 7% premarket as the broader semiconductor sector declined.

Split mechanics clear: Shareholders received seven additional shares for each held as of Nov. 9; total holdings value is unchanged.
Peers also lower: Seagate and Western Digital were set to open down, with Micron off 2% and SK Hynix down 4%.
AI infrastructure pressure: The move came as the AI infrastructure trade faced selling after Anthropic’s debut.
Adjusted pricing only: The split reduces the per-share price to one-eighth of the prior level without altering company fundamentals.
Apple quietly pulls AI agent job listing as Ternus accelerates
Lede: Apple removed a job listing Friday for an AI agent that browses the web, works across apps and writes code, signaling CEO John Ternus is pushing faster after Meta’s Muse and Anthropic gained App Store traction.

Listing details and removal: Bloomberg’s Mark Gurman reported the agent description before Apple killed the post, typical when plans leak.
Ternus timeline and pressure: CEO since Sept. 1, Ternus has pressed software chief Craig Federighi; a launch is targeted as soon as late next year.
Market reaction immediate: Anthropic fell nearly 5% late Thursday, Meta about 1%, while Apple rose and held up better than the Nasdaq 100 Friday.
Spending contrast sharp: Apple’s capex fell nearly 30% to about $9 billion last fiscal year while Microsoft, Meta, Alphabet and Amazon spent more than $600 billion; Apple rents Gemini for roughly $1 billion annually.
Verizon CEO: SpaceX needs $300 billion to match our network
Verizon CEO Dan Schulman said Elon Musk would need four to six years and about $300 billion for Starlink to field a U.S. mobile network essentially identical to Verizon’s, becoming only the sixth entrant.
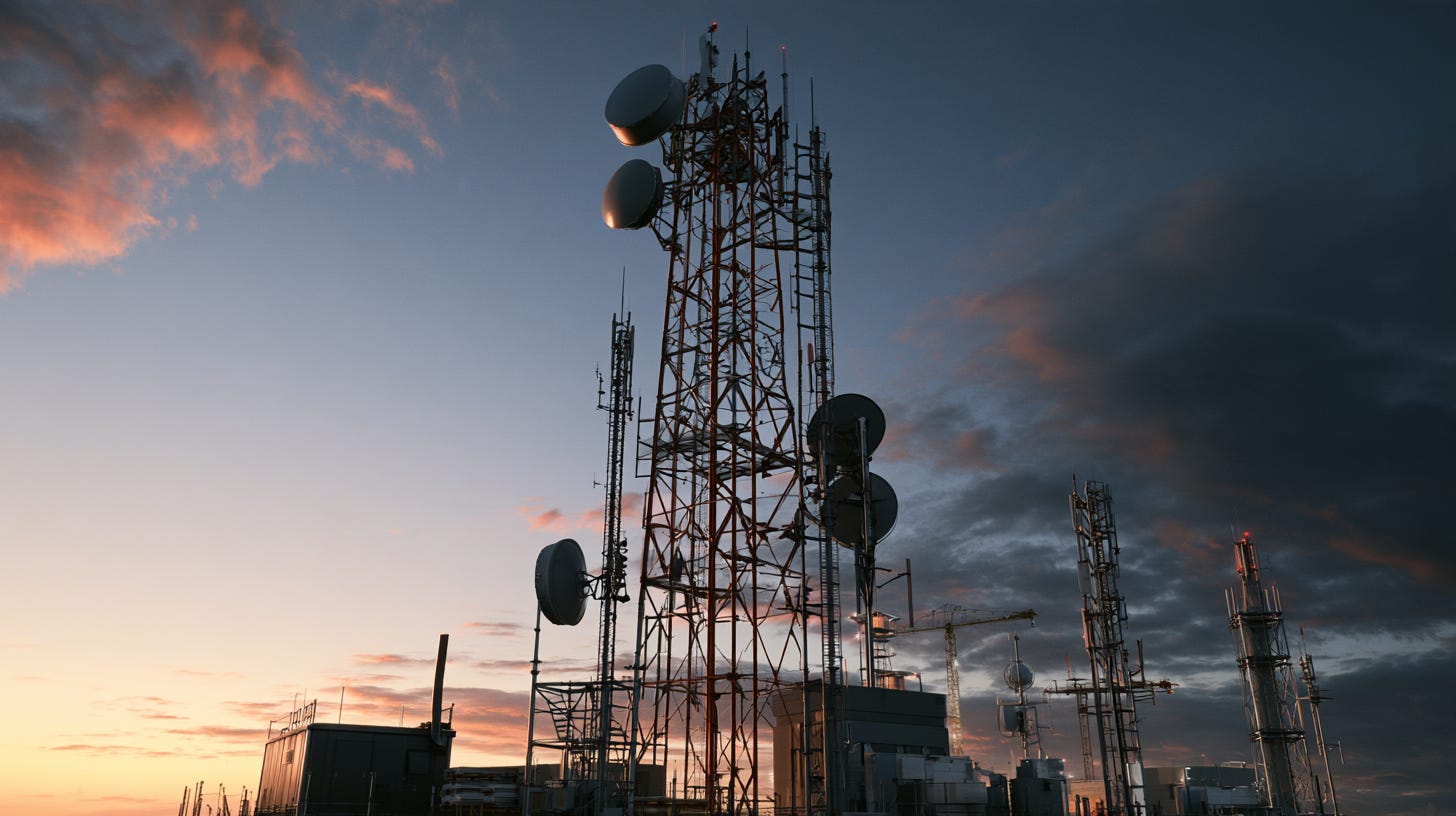
No structural edge claimed: Schulman told Fortune there is “no secret sauce” or cost advantage; the result would be a conventional network years from now.
Recent spectrum and plans: SpaceX acquired spectrum from Echostar in a $17 billion deal and plans micro cell towers as early as next year; last month’s carrier announcement cut $50 billion from major telecom market caps.
Starlink scale today: With 12 million paying subscribers, Starlink is SpaceX’s only profitable arm.
Market already competitive: Schulman expects the industry to look “radically different” in three or four years amid 6G and AI fabric, with or without SpaceX.
Johnson’s Social Security plan labeled “generational theft”
Sen. Ron Johnson’s Stop Scaring Seniors Act would cover Social Security shortfalls with Treasury borrowing to avoid a 22% cut, drawing immediate “generational theft” criticism and a $190 trillion debt warning.

Bill mechanics simple: It authorizes transfers from the general fund to the Old-Age, Survivors, and Disability Insurance Trust Fund once reserves are depleted, keeping full benefits without tax hikes or cuts.
Debt estimates stark: CRFB projects $190 trillion in added debt over 75 years in inflation-adjusted terms, or 165% of GDP; Jessica Riedl put a $45 trillion figure on the first three decades.
Expert reactions sharp: Douglas Holtz-Eakin called it “anti-reform” and “a terrible step in the wrong direction”; Maya MacGuineas said it would explode the debt and risk a crisis.
Johnson’s defense: He said the bill “simply prevents Social Security benefits from being reduced when the trust fund is depleted,” arguing the broader deficit must be addressed.

For nearly everyone outside the allocation, the price that counts is the first day's close, not the $83 offer. Of 14 big-name US listings since 2012 with a year of trading, from Facebook and Alibaba to Rivian and Arm, nine were lower a year after their first close, and only three, Arm, Reddit and CoreWeave, beat the S&P 500 over that year. I went through all 14 before the listing: https://marlowbrief.substack.com/p/anthropic-ipo-price-analysis
The detail here that matters most for Monday is the greenshoe. When underwriters exercise the overallotment, they cover their short with new shares from the company, and the stabilizing bid that normally sits at the offer price goes away. Friday it came close to $83 and bounced. Next time there's no backstop under it.
Then there's what the price has to carry. Anthropic booked about $17 billion of revenue in the third quarter, call it a $68 billion annual run rate. Computing and infrastructure ate roughly 58% of those sales. And after the S-1's reporting date it signed or amended deals for about $245 billion of additional future minimum payments. That's three and a half years of current revenue, committed before the first share traded.
None of this is a problem while growth compounds at this pace. It becomes one the quarter growth slows, becuase the payments don't slow with it. For anyone who bought above $90 on Thursday, the question isn't where the floor is, it's whether revenue keeps outrunning those commitments.